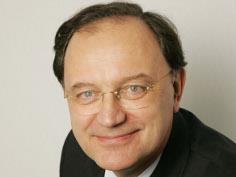
Patrick de Cambourg, president of the French standard-setting authority Autorité des Normes Comptables (ANC), couldn’t attend the French profession’s congress as he was attending other events from the international standards-setting authority, but he responded to The Accountant’s question through a telephone call. Interview by Vincent Huck
The Accountant: I went to the OEC Congress in Brussels and I heard a few criticisms comparing it to previous years where they say there were more people involved.
Patrick De Cambourg: Oh yes. It’s in Brussels for a good reason. Normally, when it’s in France people will travel from one part of France to another, but maybe they were a little surprised by the change in location and having this outside. But I find it interesting. It’s a good symbol.
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The Accountant: You thought it was a good idea to have the Congress in Brussels? And what do you think of the fact that some people didn’t think it was a good idea and didn’t even come?
De Cambourg: I think it was an excellent idea, because the future of the profession in the European Union is linked to what’s being discussed and decided at EU level. So in this respect, there are two advantages of having, from time to time, a Congress close to the European institutions. The first one is that it helps the profession to understand the relationship between the national dimension and the EU dimension. And the other advantage is that it also shows to the European institutions that the profession is dedicated and interested. For me, any national professional body has to consider both dimensions today. And a third one, which is the broader international dimension.
The Accountant: A few people were saying at the Congress that the French profession is still maybe reluctant to accept this idea. Do you agree? Do you think the French profession is a bit delayed on this and should open up more?
De Cambourg: I don’t think the French profession is behind other European citizens, quite frankly. I think in general terms there’s an element of a lack of understanding of the full picture, and that’s one of the problems with the EU, because the EU has done excellent things. Of course, some people may criticise some points because that’s always democracy. And that’s always an interesting and absolutely essential debate. However, there are a number of achievements at EU level which are commendable.
And also there’s now an allocation of tasks between the national dimensions and the European Union. So most people, most citizens, have not fully captured the EU dimension. It’s also true that in national jurisdictions, it’s an interesting sport to justify what’s going wrong by saying ‘Oh, this is Brussels’. I think French professionals are not more informed or less informed than the average citizen and that has a consequence. It’s always interesting to have such an event which helps people to fully capture this European dimension which is important.
The Accountant: Going back to the French context and particularly your organisation, the ANC, looking back at 2016 what were the highlights?
De Cambourg: I would make a number of points. Point one, France has contributed to the proper establishment of the new European Advisory Body (EFRAG) following the Maystadt reform. The final element, which was missing, which was a chairman, has been put in place, Jean-Paul Gauzès. And this establishes, I think, a real player of substance.
Point two, France has established a good relationship with the IASB, which doesn’t mean that we agree on everything. But we have a proper dialogue with the IASB. And we also a good dialogue with some standard-setters outside Europe, in particular with our colleagues from Japan and China and with our colleagues from the USA and Canada.
I’m saying this in particular because we have other relationships as well, but I personally paid a visit to China and Japan and I paid a visit also to the FASB in Norwalk, Connecticut. This is a good ground to discuss the key topics on the agenda and that’s something I find interesting from 2016.
Point three, EFRAG and ANC have been in the position to suggest a modification of IFRS 4 in line with the implementation of IFRS 9, the so-called ‘amendment’ which has been published recently by the IASB. I think this is due to a good dialogue which ANC has supported and contributed to from the very beginning. There’s still one point of contention concerning insurers within conglomerates, and I hope that we will find a proper solution at the EU level.
Point four, on the French side, we’ve launched a number of medium-term projects on a number of key topics which are necessary for the modernisation of our French GAAP. I will highlight two of those projects. One project is on the not-for-profit where we want to rethink the standard that goes back to 1999 which we need to revisit and modernise. This is a very important sector in France, as in many other developed countries. And we felt that it was needed to clarify the landscape and encourage proper accounting and management of those entities that we tend sometimes to leave aside because we concentrate on listed companies and commercial businesses. But not-for-profit is a very important sector. So that’s project number one, and we’re discussing this at our board level at the moment.
We have also launched a very important project on revenue recognition under French GAAP where we will revisit our current standards on the basis of the jurisprudence, on the basis of tax clarifications that have been issued for years, on the basis of the issues that are brought up by the accounting profession, and also on the basis of some of the points raised by IFRS 16.
It was an element that was not developed enough in the French GAAP and we have decided to integrate all those sources, clarify and extend the guidance, and create, as a consequence, more security for the proper accounting treatment of those transactions as well as their taxation. Because in France, taxation is derived from the accounting treatment, with some discrepancies, but the starting point is the accounting treatment.
We are also working on the idea of creating a forum to identify and investigate the implementation issues related to IFRS in our jurisdiction. This doesn’t mean that we are going to issue interpretation which would be controversial, but we want to operate in transparency and in a forum where all stakeholders will be represented, in order to clarify how this process works. And to support the IASB interpretation process.
In a nutshell, those five points summarise what has been achieved.
The Accountant: At the congress Olivier Guersent from the EU Parliament, made an interesting point. He was comparing the EU and the USA contributions to the IASB’s budget and he was saying that while the EU contributes more to the budget, the weight in terms of voices is the same for both. So he was critical of that. What are your thoughts?
De Cambourg: If you read the ANC response to the trustees on their proposals, which we sent in September, you will see that we share these views. We believe that the ultimate decision at IASB level should be with the people that are committed to IFRS and financing the IFRS foundation.
The Accountant: How come we ended up in a situation like this where a country, even if it’s the first economy in the world, a country that doesn’t openly believe in this project and doesn’t show any signs of wanting to adopt the standards, has an equal share at the table?
De Cambourg: I think at the moment the trustees have understood that they need to reduce that share. But if you read our letter carefully, you will see that we make proposals. In order to combine a global consensus, to a certain extent, but also a proportionate decision-making when a difficult situation arises. It makes total sense, in my view. But we are still in a context where people think that we need to be careful about de-globalising accounting standard-setting. And you need to remember that the non-USA issuers can communicate on the American market on the basis of IFRS. Therefore, there’s a level of recognition of IFRS by the USA of foreign issuers. This is important, so you justify some role, but probably not too much of a decision-making role.
By the way, on this subject, we concur with the EU Commission. On many topics we concur with the Commission, but in this case it’s pretty clear. The Commission expressed a very summarised view; we have been a little more detailed. That’s all. And by the way, a number of our colleagues in Europe, I think, will share the view. Because today, China is converting, Japan is offering the option of IFRS, the EU is applying IFRS in full with very minor exceptions. Canada, Australia and South Africa also apply it. But the EU, as it is today, is by far the biggest economy applying IFRS without offering other options. IFRS in Europe is not an option by law. It’s mandatory. And I’m not criticising the Japanese in saying that. I’m just stating a fact. And in the USA, of course which is the most critical case, a USA registrant can apply the IFRS.
The Accountant: At the congress, Guersent made another interesting comment. He said: “Since 2004 when we decided to go with IFRS, until now, we can either adopt an IFRS or not apply it. I’ve been lobbying for the EU to be able to modify partly or fully an IFRS. I want to do this, not to use it because obviously we don’t want structures which are similar to IFRS but not really IFRS, but so that we are taken a bit more seriously when we say that a particular standard doesn’t do it for us, and that it should be changed.” Any reaction to this comment?
De Cambourg: Endorsement in Europe is by no means automatic. The standard must meet the IAS Regulation criteria: European public good, true and fair view as established by the Accounting Directive, technical qualities, and this is not a formality at all. A very serious exercise must therefore be performed before the standard is endorsed. The sooner this exercise starts the better. This implies an early, constant and constructive dialogue between the European stakeholders and the IASB. Then, following this dialogue, every party has to meet its respective obligations: rejections may happen, even if they are not desirable in principle, and a ‘carve-in’ or a ‘carve-out’ out, as well as a ‘top-up’ are not a catastrophe when the overall construct and spirit are not at stake
The Accountant: You mentioned the good dialogue between the ANC and the IASB, as well as with counterparts in Japan and in China and Canada, obviously in others as well. Why is it important for the ANC to have a good dialogue with its counterparts in Japan and China?
De Cambourg: Because we confirmed that there are a lot of topics on which we share the same view and where when we want to move forward it’s good to have a global accounting community that operates in a smooth and efficient way. Let’s take an example. Japan and France are not in agreement with the idea of not recycling OCI. We feel that OCI should be recycled anyway. So it’s a point which we can progress together. On many points, we share the same view: the importance of the P&L, the fact that the border between fair value and amortised cash should be clearer, prudence, etc. So it’s good because it creates a real debate on important matters. It’s not the IASB talking to each of us, it’s more a global debate, which is good.