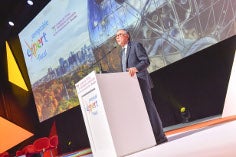
Denis Lesprit, president of the French institute for auditors (CNCC – Compagnie Nationale des Commissaires aux Comptes) talks to Vincent Huck at the French Institute of Professional Accountant’s annual congress about the EU audit reform implementation, as well as the focus for the French audit profession for the coming years
The Accountant: How was the EU audit reform implemented in France? Which options has France chosen?
Denis Lesprit: In France everything has been transposed except the deontological code which is a bit delayed because in the transposition of the reform some of the measures generated some constraint linked to extraterritoriality, so we are implementing it through the law Sapin II which is in the pipeline at the moment. Normally by the end of October, beginning of November, everything should be in order. If there are hiccups in the parliamentary process it will be for February/March.
Regarding the different options, in France with regard to the definition of PIE we are largely within the EU definition. With regard to the duration of the audit mandates we’ve chosen the option of an initial 10 years followed by six years if there’s a public tender, or 24 years if there is a joint-audit. Regarding the non-audit services, we kept the 70% limit set by the reform.
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The Accountant: So this reform is no longer a big project for the CNCC?
Lesprit: No it still is, because we still have the delegation conventions to settle. As you know, there’s a possibility for the regulator to delegate the quality control of non-PIE, inscription and formation to third parties like the CNCC.
The Accountant: Have you been consulted in the transposition?
Lesprit: An important thing to note is that the profession has spoken unanimously. All trade unions, all professionals, regardless of their sensibilities have joined up and spoken as one with regards to this reform. So this clearly gave some authority to the CNCC in front of the government.
The Ministry of Justice had told me that we would co-build the reform. But French is a very rich language, and co-building can be understood in different way.
It is clear that we had to argue, and we did to make our voice heard. I think that on the main points we have been heard even if we haven’t won on everything.
It’s sad that the idea of ‘co-building’ hasn’t been pursued the way I understand it, meaning sharing ideas to shape a project to build. The government understanding was more: “We will give you our projects and you’ll be consulted on them.”
In some instances we had to give our answers in three or four days. We’ve done it but the services of the CNCC had to be mobilised. We have done our bit. Generally speaking the profession has managed to retain its essence.
The Accountant: Meaning?
Lesprit: We have been a regulator since 2003, so we have 13 to 14 years of experience with the regulator. The EU wanted to strengthen the regulators, okay, but we are, and let’s not forget it, a regulated profession of licensed professionals. So it’s normal that we have a regulator, but it’s also normal that we have a sphere of professional judgment and self-criticism.
And this we have managed to put it in place since 2003 with the French regulator. Now, with the EU reform, we made sure that the CNCC has space for intervention. I’m thinking of the delegation conventions, our position in the regulatory procedures, also maintaining of the regional disciplinary committees. We also hope that we will maintain a role in training.
The convention of delegations will be really important in that sense and we’re waiting on what will come out to have an idea for the future.
We are entering into a period of more direct relationship with the regulator. But in the coming years, everyone will have to make their positions more precise which will result in some adjustments, a bit like tectonic plates.
The Accountant: Your mandate as president is coming to an end now. What will your successor have to focus on?
Lesprit: Normally the implementation of the reform will be finished by December. The 19 options in the reform will provoke enormous complications so this will all come back on the table in two or three years.
One of the big topics in France is that we have audit thresholds way below the EU thresholds. But for us there’s a sense and a logic in those thresholds. It’s the result of history. Our economy is driven by SMEs, and very small SMEs, so it’s logical to have low thresholds. The question is not really the level of the threshold but the reason for their levels. So we will have to communicate on this and explain that we are useful, that we bring added-value for the general interest.
The Accountant: You mean communicate at the European level?
Lesprit: No, I mean within France. But at the EU level to some extent this is already recognised as we have the proportional audit, which we have implemented in France with something we call the SME standard.
Today the regulators trust us. More than controllers we are trusted independent third parties. We have more roles in the economic landscape since 1984. We are now looking at things like delayed payments and non-financial information.
There is now an experiment in the public sector and we are opening up our activity to hospitals, trade unions and universities.
So the regulator calls on the auditors, but at the same time, and it’s a paradox, under the argument of simplification they want to raise the thresholds.
The EU is about harmonisation, but member states need to keep their specificity and that’s what we are arguing for. The problem is that now with the European construction we mix regulation and directive. A regulation should be straightforward and lead to harmonisation, but if you look at the audit reform, and in particular the regulation, I’m not too sure what it is going to harmonise. That’s why I believe it will come back on the table.
The directive, on the other hand, is a framework which gives the opportunity to the member states to keep their specificity.
Some people say why shouldn’t we just go with the same rules all the time if we are all in a single market? But the reason we can’t is that the economic fabric of each country is different. In France we have 13,500 auditors, it’s a lot. We intervene in the small businesses, but with a total unity of the profession. We have PIEs and non-PIEs and we have to preserve both and at the same time preserve one level of assurance. We have a proportionated audit, but in the small companies, like in the large ones, our opinion has the same strength. These are the challenges for the coming year.
The Accountant: You mentioned that there was an experiment in the public sector?
Lesprit: Yes, so the court of auditors will certify local authorities with the help of auditors from the firms. This trial will take place over eight years. In the first three years the methodology will be defined, then there will be five years of practice. After eight years we will draw the conclusions and see if it can be generalised.
It’s important to note that it includes all the local authorities without any thresholds. That is a very good thing because I’m convinced it will be the smaller ones that will need the auditors more.
The Accountant: When did it start?
Lesprit: It started in 2015. From 2017 to 2019 is the technical reflection; 2020 to 2022 the experiment. And from 2023 onwards, hopefully, it will be generalised.
The Accountant: And local authorities, what do you mean exactly?
Lesprit: The public administrations of town halls, departments, regions etc. There are around 40 voluntary candidates today; they should keep around 25 with a wide range of size because some are really huge and some are very small.
The Accountant: You also mentioned non-financial. What is the status in France? Is there an audit on such information?
Lesprit: Well, it is the social and environmental report which has to be reviewed. But it will increase with the implementation of the COP21.
The Accountant: There is more and more collaboration, if I understand correctly, between the CNCC and the OEC. Should we expect more?
Lesprit: It is normal and necessary if you compare with other countries. There are two things: the job and the organisation. In France, accounting is a regulated profession, while in many other countries the activity is regulated which is different. Similarly audit is a regulated profession in France; in other countries it’s only the activity that is regulated. In France chartered accountants and auditors are Siamese twins, because they qualify with the same diploma. If the two institutes were to be set apart it would be an issue and it would have consequences on the diploma.
The Accountant: If they are so much linked why have two organisations?
Lesprit: Because today the professions are regulated. If you want to link them up you will have to regulate the activities. A merger would not be a remedy, but can be an objective, and if we want to merge we need to create more synergies. So before we talk about merger we need to demonstrate that we can be organised together in a way that brings an added value.
The Accountant: You said several times he EU audit reform will come back on the table.
Lesprit: Yes, because if you look at the options in the reform, rather than harmonise, it will reveal the differences. FEE has a map of Europe with different colours for the different options taken; it’s a patchwork! And that’s why we should see the European regulators tackling the question again.
More importantly, I’m sure that in practice some case will emerge which will reveal that it’s impossible to function in this framework.
The Accountant: What type of issues do you foresee?
Lesprit: Well, in the rotation, and in the field of intervention, because some countries like Germany opted for tax as being allowed within the audit mandate and the things forbidden are not the same everywhere.
François Hurel, director general of the CNCC: Indeed the reform reveals the difference between the countries of the EU, especially between the large ones. I don’t talk about the UK because that’s another topic and it will be a topic for us.
The Accountant: In what sense?
Hurel: You will have a profession and a regulation which was built with the UK and now could become different. Imagine if the regulation is different, if the controls are not the same, if the oversight is not the same. The UK will then become a third country like the USA and the PCAOB which is quite complicated. So it brings about a possible renegotiation of everything.
But to go back to the EU reform, I agree with the president, a lot of question asked at the beginning of the reform haven’t been answered and they will have to be answered.