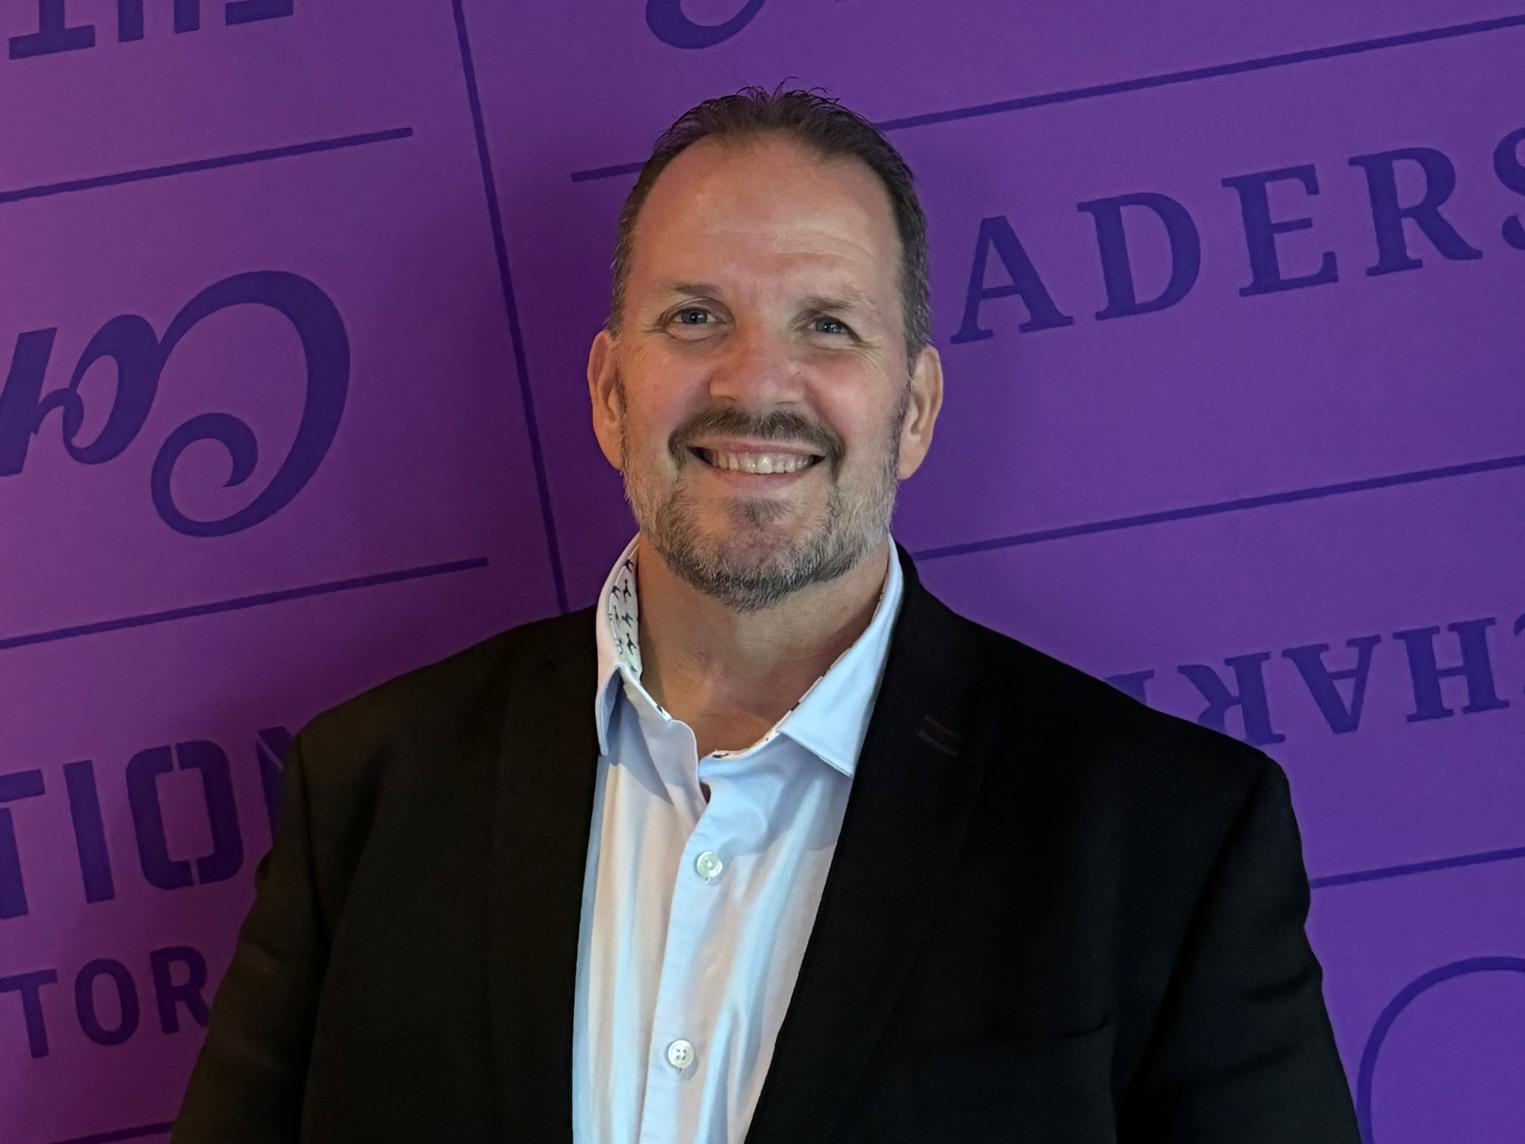
Trust underpins public perceptions of the finance and accounting profession. In fact, our profession’s entire permission to operate rests on it, writes Paul Turner, vice-president – UK and Europe at the Chartered Institute of Management Accountants (CIMA)
Without trust, we would not be able to fulfil our critical mission of being gatekeepers to the capital markets and stewards of public finances.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The problem is that trust is a declining currency in today’s fractured world where AI is increasingly being used to produce, scale and disseminate false or misleading information.
In this era of deepfakes, fake news and automated bots that manipulate public opinion, people are struggling to identify the individuals and organisations they can genuinely trust.
The implications of this loss of trust are far reaching for society, as well as business. Seven out of 10 global respondents to the 2026 Edelman Trust Barometer admitted to being “hesitant or unwilling to trust someone who is different from me”.
What is more, research by KPMG found that while 66% of people globally use AI regularly, only 46% actually trust AI systems.
Three strategies for building trust
It is against these headwinds that finance and accounting professionals face the challenge of building trust in our profession, as well as trust in our organisations, their processes and systems, and the information they provide. Rise2040, a joint research initiative between AICPA and CIMA, explored this challenge and identified that the ethical behaviour and judgement of individual finance and accounting professionals are pivotal to building trust.
As finance and accounting professionals, we can build trust in three principal ways:
- Acting with integrity. As finance and accounting professionals, we are recognised for our high ethical standards, with ethics being embedded into our training and CPD.
Maintaining – and enhancing – these standards is vital to building trust with all our stakeholders. Stakeholders want reassurance that through our work, we are holding our organisations to account and making sure they can be trusted to effectively balance performance, people and planet. - Producing accurate, high-quality work. Quality has always been an important differentiator of human performance. That will be even more the case in a world where a large volume of work is performed by machines.
Finance and accounting professionals will be expected to interrogate machine-generated output for authentic insights that can inform confident organisational decision-making. We will become market differentiators for our organisations – the knowledgeable strategists who turn complexity into clarity, to drive better results. - Ensuring the integrity of data. Robust datasets are essential for the deployment of effective AI systems. If AI uses poor, biased or incomplete data, there is increased risk of hallucination, discriminatory outcomes, operational inefficiencies and even model collapse.
Finance and accounting professionals can provide effective oversight of data by enforcing quality standards, implementing controls and establishing guidelines around use. In turn, this will underpin the ethical, responsible use of AI systems within our organisations and mean the outputs they generate can be relied upon.
There is an adage that says: “Trust takes years to build, seconds to break, and forever to repair.” In the fast-moving age of AI, this is arguably truer now than ever before.
The finance and accounting profession cannot afford to be complacent about trust as we move into the future – we should not simply assume that we are trusted by our stakeholders. Instead, we must be proactive about building trust through what we say and do – as well as through our use of technology and our governance of data.
If we are to retain our privileged roles as gatekeepers to the capital markets and stewards of public finances, we must also assume a third, highly important mantle. That is to be the guardians of trust.