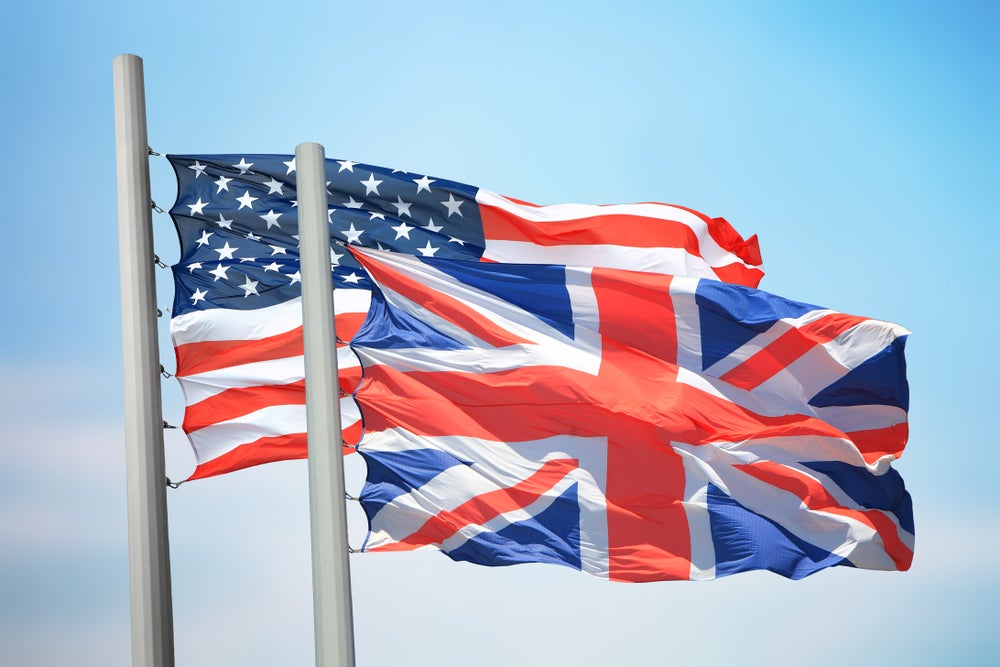
Expanding into the UK is a milestone worth celebrating. It is also the moment your numbers start living in two accounting worlds at once. The balance sheet that satisfies your board in the US will not, on its own, satisfy a UK statutory filing, and the gap between the two is wider than most finance teams expect before they arrive. Nick Whitehead, audit partner at BPM UK, writes
The good news is that the differences are knowable and manageable. The teams that struggle are usually the ones that treat UK reporting as a translation exercise rather than a genuinely different framework.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
Here is what to understand before you make the move.
Two frameworks, two philosophies
The starting point is philosophical. US GAAP, issued by the Financial Accounting Standards Board (FASB), is generally regarded as a more rules-based framework, characterised by detailed and prescriptive guidance intended to promote consistency in application and reduce diversity in practice. In contrast, UK GAAP, primarily embodied in FRS 102 and overseen by the Financial Reporting Council (FRC), is more principles-based and rooted in the same conceptual approach as international accounting standards. As a result, it typically places greater emphasis on professional judgement when applying accounting requirements to specific facts and circumstances.
That distinction drives many of the differences that follow. Where a US controller may expect detailed guidance for a specific transaction, a UK preparer is more often required to apply broader accounting principles and exercise professional judgement in determining the appropriate treatment.
Neither approach is inherently superior, but the different emphasis on rules versus judgement can lead to different accounting outcomes for the same transaction. Those differences often become most apparent during the consolidation process.
The reporting landscape that US teams do not expect
UK financial reporting is governed by the Companies Act 2006 and accounting standards issued by the FRC. Certain entities, particularly those operating in regulated sectors, may also be subject to requirements imposed by the Financial Conduct Authority (FCA).
Two features often surprise companies arriving from the US. First, statutory accounts are filed publicly at Companies House, meaning the level of financial privacy often associated with US private companies does not typically exist in the UK. Second, UK entities can choose from a number of reporting frameworks, including FRS 102, FRS 101 and full IFRS, rather than being required to adopt a single reporting standard.
Understanding which reporting framework applies to your UK entity is one of the first practical decisions management must make, as it influences everything from recognition and measurement requirements to disclosures, filing obligations and audit considerations.
Where the numbers change
Several recurring differences under the pre-2026 version of FRS 102 deserved careful consideration when modelling a UK entity within a US group:
- Revenue recognition. US GAAP applies the prescriptive five-step model of ASC 606. FRS 102 historically adopted a less prescriptive approach, with recognition based on the transfer of significant risks and rewards and the stage of completion of services. This could result in different recognition patterns for certain contracts and cross-border arrangements.
- Leases. Under US GAAP, ASC 842 brings virtually all leases longer than 12 months onto the balance sheet. By contrast, under the previous version of FRS 102, operating leases typically remained off balance sheet, with rental costs recognised through the income statement over the lease term.
- Goodwill and intangibles. US GAAP does not amortise goodwill and indefinite-lived intangible assets, instead requiring periodic impairment testing. Under UK GAAP, goodwill is amortised over its estimated useful economic life, often producing a significantly different earnings profile.
- Asset revaluation. UK GAAP permits fixed assets to be revalued to market value; US GAAP holds them at historical cost.
- Inventory and impairment. US GAAP permits the use of last-in, first-out (LIFO) inventory costing, whereas UK GAAP prohibits it. The frameworks also adopt different approaches to impairment testing. US GAAP generally applies an undiscounted cashflow recoverability test before measuring an impairment loss, while UK GAAP determines impairment by reference to recoverable amount, which may require the use of discounted cash flow techniques. As a result, the timing and amount of impairment charges can differ between the two frameworks.
None of these are insurmountable, but each can move reported profit or the balance sheet, and a US parent reading UK results without adjustment can draw the wrong conclusion.
Why 2026 matters
The picture is not static. The FRC’s Periodic Review 2024 introduced significant amendments to FRS 102, effective for accounting periods beginning on or after 1 January 2026. Two changes stand out: a new revenue model based on the international five-step approach, and a lease model that brings most leases on balance sheet. In practical terms, UK GAAP is moving closer to US GAAP on two of the areas that have caused the most friction.
For a finance team planning an expansion now, that is both an opportunity and a warning. The gap on revenue and leases is narrowing, but the transition itself creates work, and teams reporting under both frameworks will need to manage the change carefully.
The audit trigger most teams miss
Here is the point that catches out the most sophisticated finance functions. UK statutory audit thresholds are written into company law, and for a subsidiary of a non-small group they are assessed at the global group level, not the local UK level. A US business turning over tens of millions of dollars can trigger a mandatory UK audit for a subsidiary with only two or three people on the ground.
This surprises not only overseas finance teams but sometimes local accountants who do not handle international groups regularly. The audit is confined to the UK operation, so the marginal cost is modest, but the obligation is a legal one, and it is far better understood before incorporation than discovered afterwards.
Consolidation and the two-sets-of-books reality
Finally, remember that the reporting process does not end with the UK statutory accounts. For most US-owned groups, the UK results will ultimately need to be converted to US GAAP for consolidation and group reporting purposes. That may be achieved through a formal reconciliation process, a detailed mapping schedule, or parallel accounting records, depending on the complexity of the business. Whichever approach is adopted, establishing the process early is far preferable to scrambling to reconcile differences under reporting deadlines.
A well-planned reporting bridge not only improves efficiency but also reduces the risk of surprises as the UK operation begins to scale.
A short pre-expansion checklist
Before establishing your UK entity, confirm which reporting framework will apply, model the impact of any material UK GAAP differences, assess whether a statutory audit will be required by reference to the worldwide group, and agree a US GAAP reconciliation process with your parent-company finance team. Align reporting timetables and information requirements at the outset, as doing so will save significant time and effort later.
The differences between US and UK GAAP are real, but they are navigable with the right preparation. Understanding them early turns a potential source of uncertainty into simply another part of a well-planned expansion.