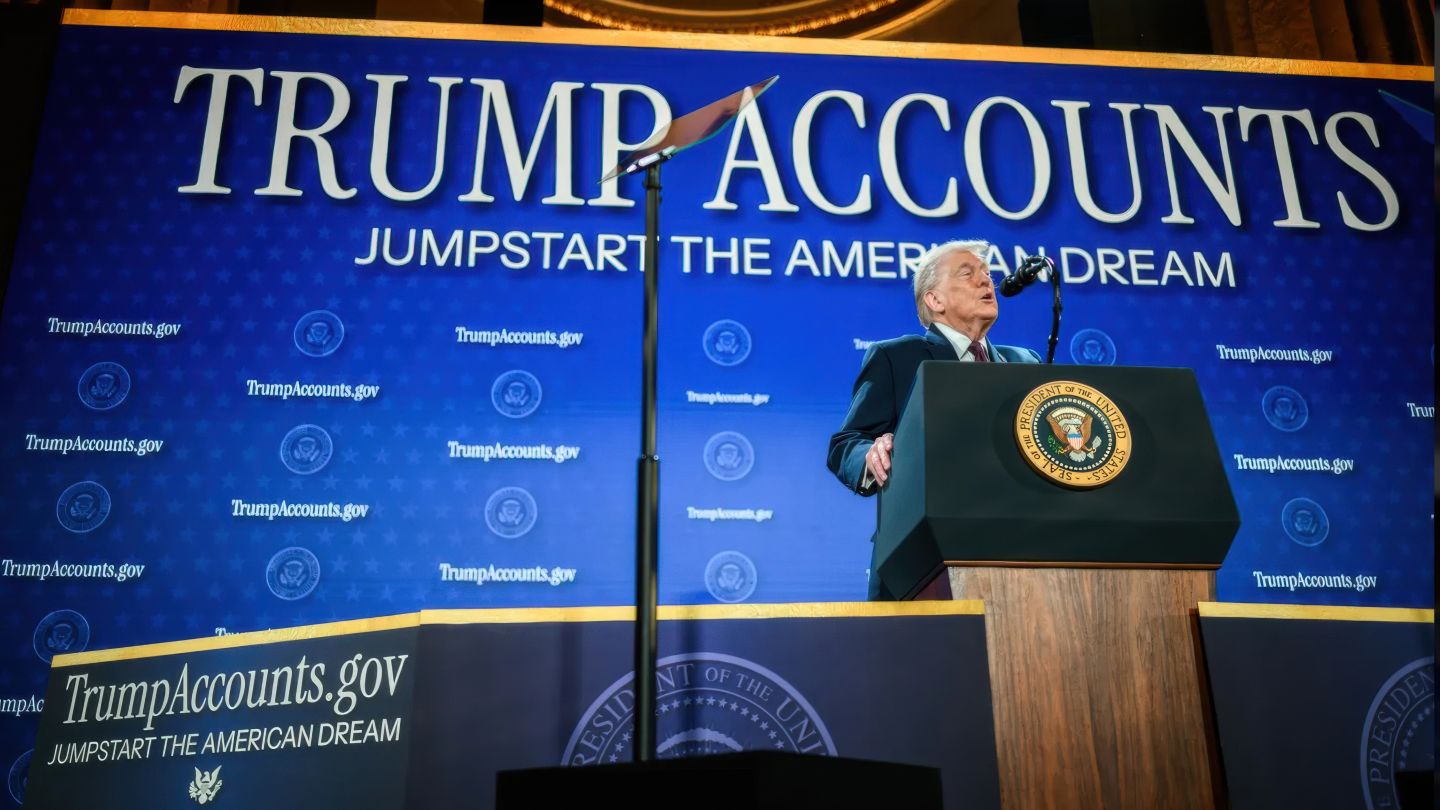
The American Institute of CPAs (AICPA) has submitted recommendations to the US Treasury and the Internal Revenue Service (IRS) on proposed regulations governing employer contributions to Trump accounts.
The submission states that key segments of the regulatory proposal are “administratively burdensome” and could prove “difficult” for organisations to satisfy.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The proposed regulations refer to employer-sponsored Trump account contribution programmes established under Internal Revenue Code (IRC) Section 128.
The mechanism allows enterprises to provide tax-exempt funding directly into accounts maintained by personnel or their dependents.
Annual deposits are capped at $2,500 per worker across 2026 and 2027, with inflation indexing applied in subsequent tax years.
The operational structure resembles dependent care assistance programmes established under Section 129.
Sponsoring firms must maintain a standalone written plan and adhere to statutory worker notifications, annual reporting, and “non-discrimination” mandates.
The published regulations specify compliance benchmarks covering account validation, cafeteria plan salary-reduction arrangements, contribution ceilings, plan documentation, trustee interaction and workforce certifications.
They also outline remediation pathways for administrative errors and non-discrimination failures, as well as formal non-discrimination testing standards under Sections 128 and 129.
In response, the AICPA called for simplified compliance mechanisms for Trump account contribution programs, alongside establishing a “reasonable method” to verify accounts and transfer payments.
The professional body also advised creating a “standard process” for correspondence with Trump account trustees, paired with a workable selection protocol for trustees.
Further technical requests include expanding “flexibility” within non-discrimination requirements, resolving payroll reporting procedures after non-discrimination failures, and coordinating frameworks with the Individual Retirement Account Employee Plans Compliance Resolution System programme.
To address initial implementation hurdles, the AICPA urged the authorities to grant transition relief and postpone the funding deadline for 2026 Trump account contributions into 2027.
AICPA Tax Policy and Advocacy senior manager Michelle Zou said: “The AICPA’s letter addresses practical compliance challenges to sections that could make Trump account programmes difficult to implement. The goal of our recommendations is to reduce uncertainty and administrative burdens for employers and tax practitioners.”