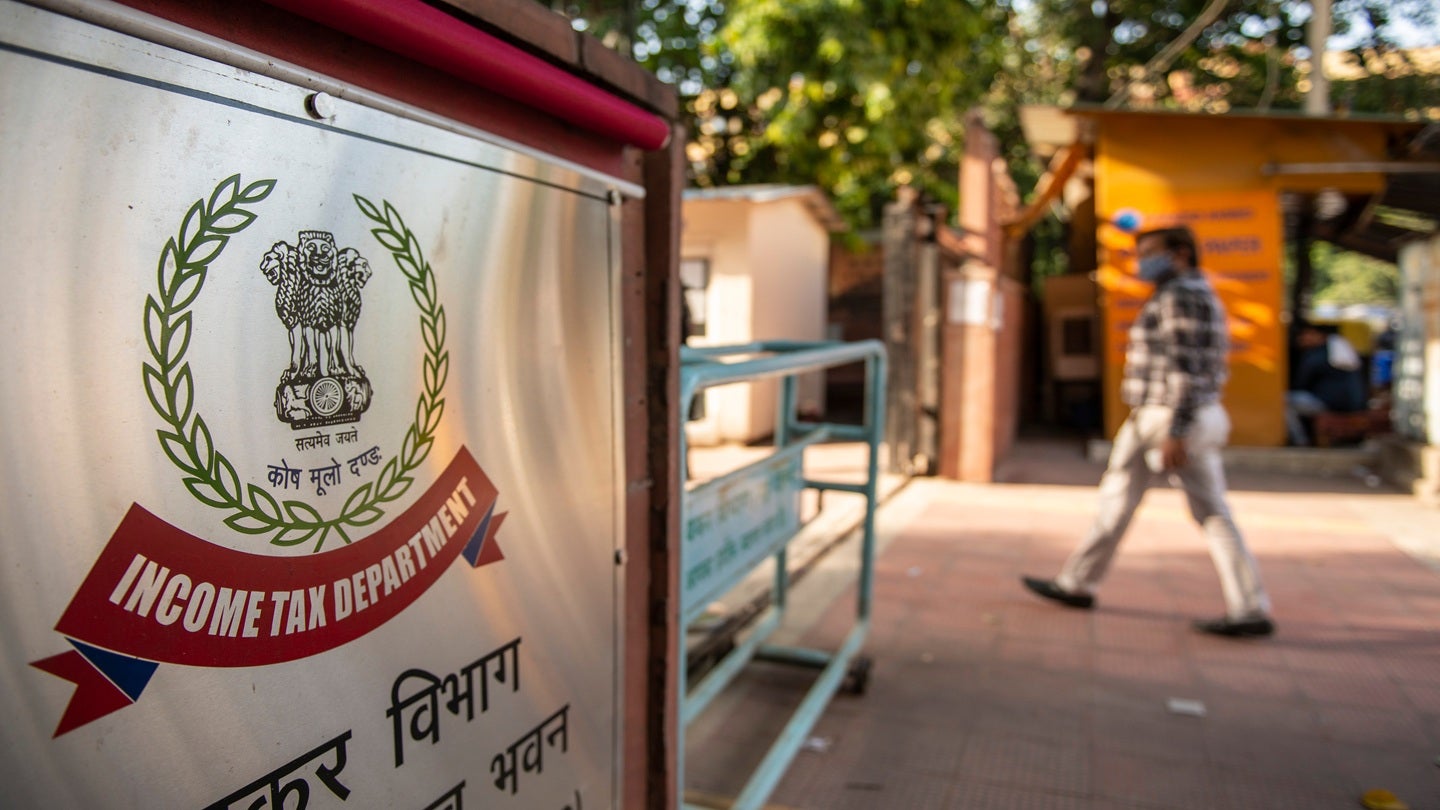
India’s Central Board of Direct Taxes (CBDT) has removed provisions concerning arrest and detention from the procedure for recovering tax arrears.
The statutory authority has also extended by six months the registration deadline for valuers and authorised income tax practitioners under the Income-tax Act, 2025 framework.
Go deeper with GlobalData
Access deeper industry intelligence
Experience unmatched clarity with a single platform that combines unique data, AI, and human expertise.
The changes were notified as part of the Income-tax (Fourth Amendment) Rules, 2026.
It involved amending Rule 225 of the Income-tax Rules, 2026, which covers the recovery of tax arrears, according to a Business Standard report.
Under the amendment, a provision referring to the power of arrest has been omitted, while words “except arrest and detention” have been removed from another provision.
Several other sub-rules under Rule 225 have also been deleted.
The amendments to Rules 2 to 4, including Rule 225, apply retrospectively from 1 April 2026.
The CBDT has separately extended the registration period for valuers and authorised income tax practitioners under Rules 246 and 256. The previous deadline of 30 September 2026 has been moved to 31 March 2027.
The notification replaces Form 169, which is used to apply for registration as a valuer under Section 514 of the Income-tax Act, 2025.
The revised form requires applicants to submit personal details, information about the asset class for which registration is sought, educational qualifications, previous employment and professional experience.
The form covers 11 asset classes including immovable property, securities, machinery and plant, jewellery and works of art, among others.
The CBDT has also updated Form 171, the application used to register as an authorised income tax practitioner.
Under the new guidelines, applicants must now provide details regarding their educational qualifications and existing registrations.
Additionally, they must certify that they have practiced before income tax authorities for a minimum of one year.